Short answer: if you are hurt when your car hits a deer in Michigan, your own auto insurer pays your medical bills and lost wages under no-fault (PIP), because a deer strike is still an "accident arising out of the use of a motor vehicle." Damage to the car is a comprehensive claim, not a collision claim, and there is no mini-tort against a deer. You can sue another person only when another driver caused the crash: the one who swerved into your lane, or the one who hit you from behind when you braked. Motorcyclists are the exception, and the gap can be brutal. The details, with the 2025 numbers, are below.
The 2025 numbers: 58,271 crashes, 13 deaths, one county over 2,200
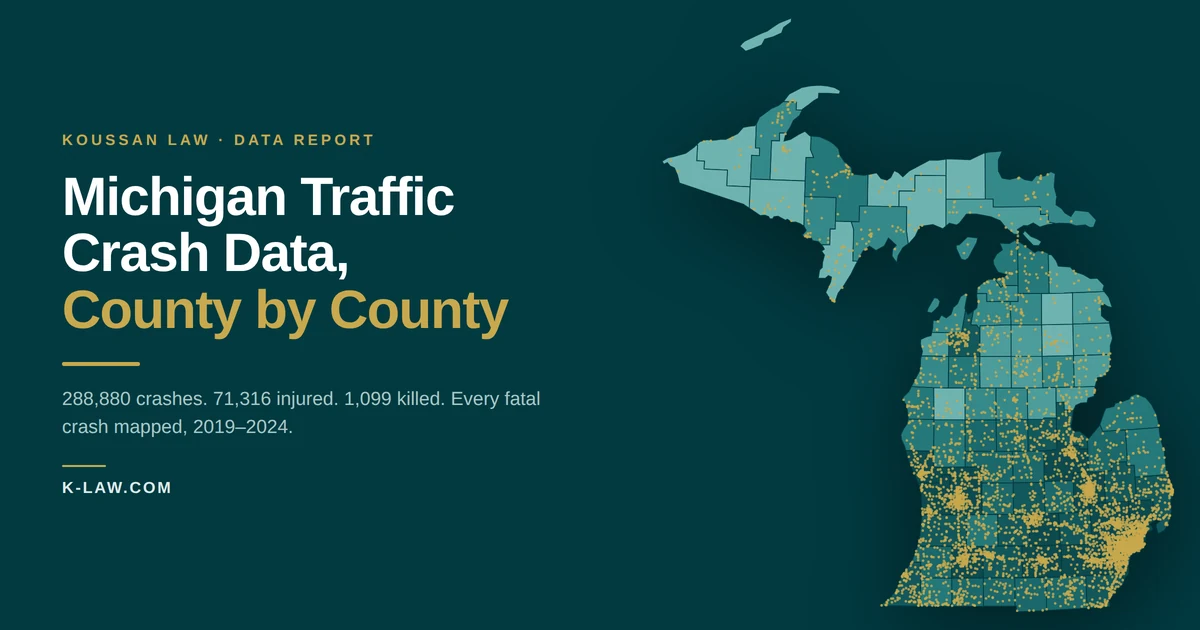
Michigan police agencies reported 58,271 motor vehicle-deer crashes in 2025, with 13 fatal crashes and 1,724 people injured, according to the Michigan Traffic Crash Facts deer report compiled from UD-10 reports filed with the Michigan State Police. The same report series counted 14 deaths the year before.
Where they happen is not where most drivers expect. The counties with the most deer crashes in 2025 were Oakland (2,259), Kent (1,960), Genesee (1,659), Jackson (1,557), Ottawa (1,498), Allegan (1,476), Washtenaw (1,404), Lapeer (1,386), Ingham (1,352) and Calhoun (1,306). Wayne County had 698 and Macomb 764. Marquette County, home to our Upper Peninsula office, had 432. Oakland County, with its parkways, lake roads and long commutes at dawn, leads the state by a wide margin.
Timing matters more than location. November alone produced 9,821 crashes, and 40.9 percent of the year's deer crashes happened in October, November and December. The single worst window is 6:00 to 8:59 in the morning, which accounted for 24.2 percent of all deer crashes (14,127). That is the morning commute during the rut, when deer are moving and the sun is low.
State Farm's claims data for July 2024 through June 2025 put Michigan fourth in the nation for the likelihood of a driver hitting an animal, more than twice the national average, as Michigan Public reported.
Who pays for your injuries: your own no-fault policy
Michigan's no-fault act pays personal protection insurance benefits for accidental bodily injury "arising out of the ownership, operation, maintenance or use of a motor vehicle as a motor vehicle" (MCL 500.3105). Nothing in that sentence requires another driver, and nothing requires fault. A deer coming through the windshield on M-24 is covered the same way a rear-end collision on I-696 is covered.
That means PIP benefits from your own insurer:
- Medical expenses for reasonably necessary care, up to the PIP medical level you chose on your policy. If you selected unlimited coverage, it is unlimited. If you selected a capped level, the cap applies, and your health insurance or Medicare rules decide what happens above it.
- Wage loss at 85 percent of what you would have earned, for up to three years, subject to the monthly maximum set each year by the state.
- Replacement services up to $20 per day for the household work you can no longer do.
- Attendant care if your injuries require it.
Two deadlines govern these benefits. You must give your insurer written notice of the injury within one year of the crash, and if you have to sue for unpaid benefits, recovery is generally limited to expenses incurred in the year before the suit is filed (MCL 500.3145). Deer-crash injuries are exactly the kind that get minimized at the scene ("I'm fine, the car took the hit") and turn into a neck or back claim three months later. Get checked, and put the insurer on written notice early. Our guide to Michigan no-fault benefits walks through each benefit in more detail.
If you were a passenger, the same benefits apply, generally through the policy on the vehicle you were in or your own household policy, in the priority order the statute sets. If you were injured as a pedestrian or cyclist by a car that swerved to miss a deer, you also have a PIP claim, and the driver's conduct is a separate question covered below.
Who pays for the car: comprehensive, not collision, and no mini-tort
Insurance companies treat striking an animal as a comprehensive loss, the same category as a tree branch or a hailstorm. If you carry comprehensive coverage, the deer damage is paid minus your comprehensive deductible. If you swerved and hit a guardrail, a tree or another car without touching the deer, most insurers call that a collision claim, which usually carries a higher deductible and can affect your rate. It is worth telling the adjuster precisely what happened.
Michigan's mini-tort, the claim of up to $3,000 for vehicle damage against an at-fault driver (MCL 500.3135), needs an at-fault driver. There is nobody to bring it against when the only other party had antlers. If you carry no comprehensive coverage, the repair is yours.
Report the crash. Michigan requires a driver to report immediately to the police any crash involving injury, death, or property damage of $1,000 or more (MCL 257.622), and deer damage on a modern vehicle clears that threshold almost every time. The UD-10 report is also the document the comprehensive adjuster will ask for.
When someone else owes you
The deer is never a defendant. Another driver can be.
The driver behind you. You see the deer, you brake hard, and the pickup behind you does not. Michigan law presumes the rear driver was negligent in a rear-end collision unless he can rebut it (MCL 257.402). "A deer ran out" is his problem too; he was required to keep an assured clear distance. If your injuries meet the threshold, you have a claim against him for pain and suffering and for economic losses that exceed no-fault, and a mini-tort claim for your deductible.
The driver who swerved into you. A driver who leaves his lane to avoid an animal and strikes an oncoming or adjacent vehicle has to justify that choice. The sudden emergency doctrine can excuse a reasonable reaction to a true emergency, but it does not excuse speeding, distraction, following too closely, or driving too fast for a stretch of road that is posted for deer.
The threshold. To recover non-economic damages from an at-fault driver in Michigan, your injury must be a serious impairment of body function, a permanent serious disfigurement, or death (MCL 500.3135). A fractured wrist that keeps you from working, a concussion with lasting symptoms, or a back injury that changes how you live generally qualifies. Soreness that resolves in two weeks generally does not.
Our Michigan car accident lawyers handle these claims every day, and the analysis starts with the police report and the timeline, so preserve both.
Motorcyclists: the coverage gap nobody warns you about
A motorcycle is not a "motor vehicle" under the no-fault act. A rider injured in a crash that involves a car or truck claims PIP benefits from the motor vehicle's insurer in the order MCL 500.3114 sets. A rider who hits a deer with no car involved has no no-fault claim at all. The medical bills fall on the rider's health insurance, on the optional medical benefits some motorcycle policies sell, or on the rider.
That gap matters because deer are uniquely dangerous to riders. A 2025 study reported by WCMU found a high risk of injury or death when a motorcycle and a deer meet. If you ride in Michigan from September through December, check your motorcycle policy for medical payments coverage before the season, not after. If a car was involved in any way, even without contact, talk to our motorcycle accident attorneys before you accept an insurer's position that no motor vehicle was "involved."
The first 24 hours after a deer strike
- Brake, do not swerve. Every safety agency in the state says the same thing, and the crash data explains why: the car that stays in its lane usually has a comprehensive claim; the car that leaves the road usually has injuries.
- Pull over, turn on your hazards, and stay away from the animal. An injured deer can kick.
- Call 911 and get a police report. Injury or damage over $1,000 makes the report mandatory, and it protects your claim either way.
- Photograph everything: the vehicle, the road, the sign if there was one, and your injuries.
- Get medical care the same day, even for "just soreness." Neck, back and head injuries from a sudden stop declare themselves late.
- Notify your insurer in writing and keep a copy. That starts the one-year PIP clock on your side.
- Do not give a recorded statement about your injuries until you know what they are. Describing the damage to the car is fine; guessing about your body is not.
Frequently asked questions
Does hitting a deer raise my insurance rates in Michigan? A comprehensive claim is generally treated as a not-at-fault loss, and Michigan's reform law limits the factors insurers may use in setting rates. Ask your agent how your carrier handles comprehensive claims before you assume the worst.
Can I sue the state or county because a deer crossing was not marked? Almost never. Governmental agencies are immune for most road conditions, and a wild animal on the road is not a highway defect. Claims against government bodies also carry a 120-day notice requirement, which is a trap even in the rare cases that qualify.
Does my passenger get benefits if I hit a deer? Yes. Passengers injured in the crash claim PIP benefits under the no-fault priority rules, usually starting with their own household's policy and then the policy on the vehicle.
What if I was in a rental or a work vehicle? The no-fault benefits still exist; the question is which policy is first in line. The priority rules are technical, and the wrong insurer will happily deny while you wait. Get the claim to the right carrier early.
Do I have a case if the deer came out of nowhere? For your own no-fault benefits, yes, without proving anyone did anything wrong. For a claim against another driver, only if another driver's negligence caused or worsened the crash.
Talk to a Michigan car accident lawyer
If a deer crash left you with more than a repair bill, the free consultation is worth twenty minutes. We will tell you which carrier owes your benefits, whether any driver's conduct gives you a claim beyond no-fault, and what the one-year deadlines mean for you. Call Koussan Law at (313) 800-0000 or request a free consultation. Offices in Detroit, Dearborn Heights and Marquette; we serve clients across Michigan in English, Spanish and Arabic.
Important: This is not legal advice
This article is general information about Michigan personal injury law. It is not legal advice and should not be relied on as a substitute for consultation with a licensed Michigan attorney about your specific situation. The laws, deadlines, procedures, and frameworks here are general guidelines that may or may not apply to your case.
Every personal injury case turns on its own unique facts. The timing, the parties, the evidence, the jurisdiction, the insurance available, and dozens of other variables can change the legal analysis. Do not rely on anything written on this website to make decisions about your case.
If you have been injured in Michigan, the only responsible step is to speak with a licensed Michigan attorney about your specific facts. Call Koussan Law at (313) 800-0000 for a free consultation, or contact a different Michigan personal injury attorney of your choosing.
Reading this article does not create an attorney-client relationship with Koussan Law. Past results do not guarantee future outcomes.