Michigan No-Fault Law, section by section › MCL 500.3107d
Election to not maintain personal protection insurance benefit coverage; proof of qualified health coverage; form; failure to make election; termination of qualified health coverage; definitions.
In plain terms
A named insured with Medicare Parts A and B may elect not to carry PIP medical coverage at all if the spouse and resident relatives also have qualified health coverage or their own PIP medical. If that health coverage ends, the household has 30 days to buy PIP medical; anyone hurt in the gap without another policy loses PIP medical for the injury but can claim through the assigned claims plan. Defines "qualified health coverage" (no motor vehicle exclusion and an annual deductible of $6,000 or less, as adjusted by DIFS).
How this section works in practice
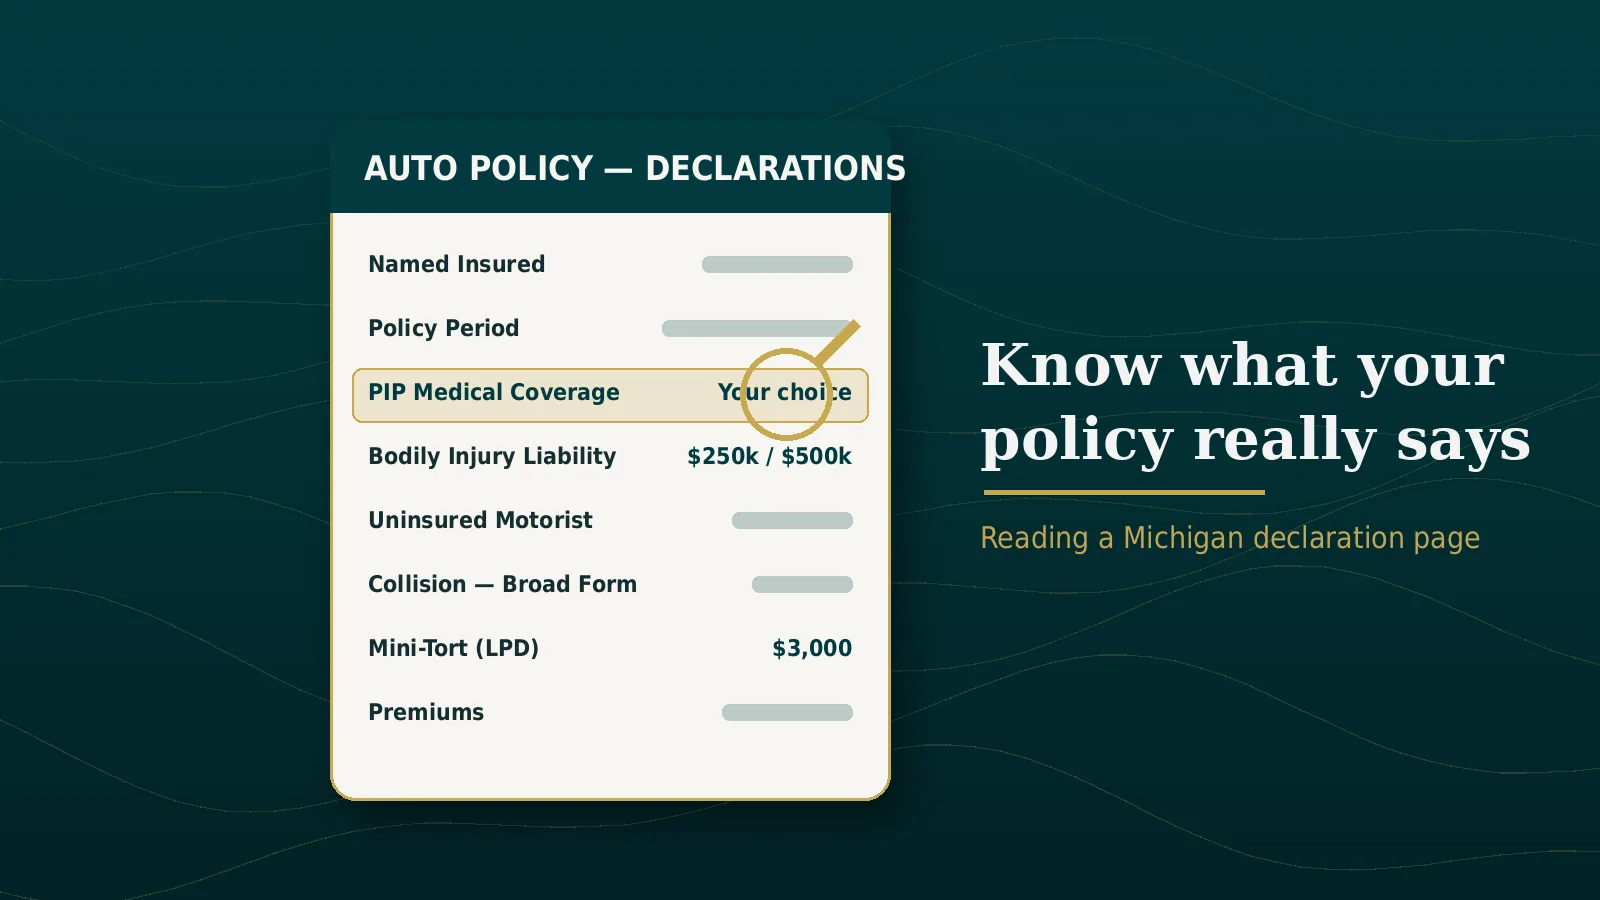
People on Medicare may opt out of PIP medical coverage entirely. The named insured must have Medicare Parts A and B, and the spouse and every resident relative must have either qualified health coverage or PIP medical under another policy. Qualified health coverage means a health plan that does not exclude motor vehicle injuries and has an individual deductible of $6,000 or less (a figure DIFS adjusts each July), or Medicare Parts A and B.
The risk sits in subsection (6). If the qualifying health coverage ends during the policy term, the household has 30 days to buy PIP medical. Anyone injured in that 30-day window without another applicable policy loses PIP medical for that injury and is left with the assigned claims plan, whose medical benefits are capped under section 3172(7). Insurers may not refuse or surcharge someone who missed the deadline, but the lost benefits for that accident are not restored. Medicare itself is a limited substitute: it pays a fee schedule, it pays nothing for attendant care or replacement services, and it does not pay wage loss. Families who choose this option should keep the health-coverage paperwork current and tell the insurer the moment anything changes.
Text of MCL 500.3107d
Sec. 3107d.
(1) For an insurance policy that provides the security required under section 3101(1) and is issued or renewed after July 1, 2020, the applicant or named insured may, in a way required under section 3107e and on a form approved by the director, elect to not maintain coverage for personal protection insurance benefits payable under section 3107(1)(a) if the applicant or named insured is a qualified person, and if the applicant's or named insured's spouse and any relative of either that resides in the same household have qualified health coverage or have coverage for benefits payable under section 3107(1)(a) from an insurer that provides the security required by section 3101(1).
(2) An applicant or named insured shall, when requesting issuance or renewal of a policy under subsection (1), provide to the insurer a document from the person that provides the qualified health coverage stating the names of all persons covered under the qualified health coverage.
(3) The form required under subsection (1) must do all of the following:
(a) Require the applicant or named insured to mark the form to certify whether all persons required to be qualified persons under subsection (1) are qualified persons.
(b) Disclose in a conspicuous manner that qualified persons are not obligated to but may purchase coverage for personal protection insurance coverage benefits payable under section 3107(1)(a).
(c) State, in a conspicuous manner, the coverage levels available under section 3107c.
(d) State, in a conspicuous manner, the benefits and risks associated with not maintaining the coverage.
(e) State, in a conspicuous manner, that if during the term of the policy the qualified health coverage ceases, the person has 30 days after the effective date of the termination of qualified health coverage to obtain insurance that provides coverage under section 3107(1)(a) or the person will be excluded from all personal protection insurance coverage benefits under section 3107(1)(a) during the period in which coverage under this section was not maintained.
(f) Provide a way for the applicant or named insured to mark the form to acknowledge that he or she has read the form and understands it and that he or she understands the options available to him or her.
(g) If all persons required to be qualified persons under subsection (1) are qualified persons, provide the person a way to mark the form to elect to not maintain the coverage.
(h) Require the applicant or named insured to sign the form.
(4) If an insurance policy is issued or renewed as described in subsection (1) and the applicant or named insured has not made an effective election under subsection (1), the policy is considered to provide personal protection benefits under section 3107c(1)(d).
(5) An election under this section applies to the applicant or named insured, the applicant or named insured's spouse, a relative of either domiciled in the same household, and any other person who would have had a right to claim personal protection insurance benefits under the policy but for the election.
(6) If, during the term of an insurance policy under which coverage for personal protection insurance benefits payable under section 3107(1)(a) are not maintained under this section, the persons required to have qualified health coverage under subsection (1) cease to have qualified health coverage, all of the following apply under this subsection:
(a) Within 30 days after the effective date of the termination of qualified health coverage, the named insured shall obtain insurance that includes coverage under section 3107(1)(a).
(b) An insurer that issues policies that provide the security required by section 3101(1) shall not refuse to prospectively insure, limit coverage available to, charge a reinstatement fee to, or increase the insurance premiums for a person who is an eligible person, as that term is defined in section 2103, solely because the person previously failed to obtain insurance that provides coverage for benefits under section 3107(1)(a) in the time required under subdivision (a).
(c) If the applicant or named insured does not obtain insurance as required under subdivision (a) and a person to whom the election under this section applies as described in subsection (5) suffers accidental bodily injury arising from a motor vehicle accident within the 30-day period, unless the injured person is entitled to coverage under some other policy, the injured person is not entitled to be paid personal protection insurance benefits under section 3107(1)(a) for the injury but is entitled to claim benefits under the assigned claims plan.
(7) As used in this section:
(a) "Consumer Price Index" means the most comprehensive index of consumer prices available for this state from the United States Department of Labor, Bureau of Labor Statistics.
(b) "Qualified health coverage" means either of the following:
(i) Other health or accident coverage to which both of the following apply:
(A) The coverage does not exclude or limit coverage for injuries related to motor vehicle accidents.
(B) Any annual deductible for the coverage is $6,000.00 or less per individual. The director shall adjust the amount in this sub-subparagraph on July 1 of each year by the percentage change in the medical component of the Consumer Price Index for the preceding calendar year. However, the director shall not make the adjustment unless the adjustment, or the total of the adjustment and previous unadded adjustments, is $500.00 or more.
(ii) Coverage under parts A and B of the federal Medicare program established under subchapter XVIII of the social security act, 42 USC 1395 to 1395lll.
(c) "Qualified person" means a person who has qualified health coverage under subdivision (b)(ii).
History: Add. 2019, Act 21, Imd. Eff. June 11, 2019 ;-- Add. 2019, Act 22, Imd. Eff. June 11, 2019
Source: MCL 500.3107d at legislature.mi.gov (official text). Text as published in the 2025 Michigan Compiled Laws; reviewed by Koussan Law on September 15, 2026.
Sections this one refers to
- MCL 500.3101: Who Must Carry No-Fault Insurance
- MCL 500.3107e: How Coverage Selections Must Be Made
- MCL 500.3107: What PIP Pays: Medical, Wage Loss, Services
- MCL 500.3107c: Choosing a PIP Medical Coverage Level
Sections that refer to this one
- MCL 500.3101: Who Must Carry No-Fault Insurance
- MCL 500.3104: The Michigan Catastrophic Claims Association
- MCL 500.3107c: Choosing a PIP Medical Coverage Level
- MCL 500.3107e: How Coverage Selections Must Be Made
- MCL 500.3109a: Coordinated PIP and Health Insurance
- MCL 500.3114: Priority: Which Insurer Pays PIP
- MCL 500.3135: Serious Impairment Threshold and Mini Tort
- MCL 500.3172: Claiming Through the Assigned Claims Plan
Practice pages
Important: This is not legal advice
This article is general information about Michigan personal injury law. It is not legal advice and should not be relied on as a substitute for consultation with a licensed Michigan attorney about your specific situation. The laws, deadlines, procedures, and frameworks here are general guidelines that may or may not apply to your case.
Every personal injury case turns on its own unique facts. The timing, the parties, the evidence, the jurisdiction, the insurance available, and dozens of other variables can change the legal analysis. Do not rely on anything written on this website to make decisions about your case.
If you have been injured in Michigan, the only responsible step is to speak with a licensed Michigan attorney about your specific facts. Call Koussan Law at (313) 800-0000 for a free consultation, or contact a different Michigan personal injury attorney of your choosing.
Reading this article does not create an attorney-client relationship with Koussan Law. Past results do not guarantee future outcomes.